The Hagag Baku Deal in Full: Two Plots, 3,500 Units, $93m of Land
Published on 2026-10-23 · 7 min read
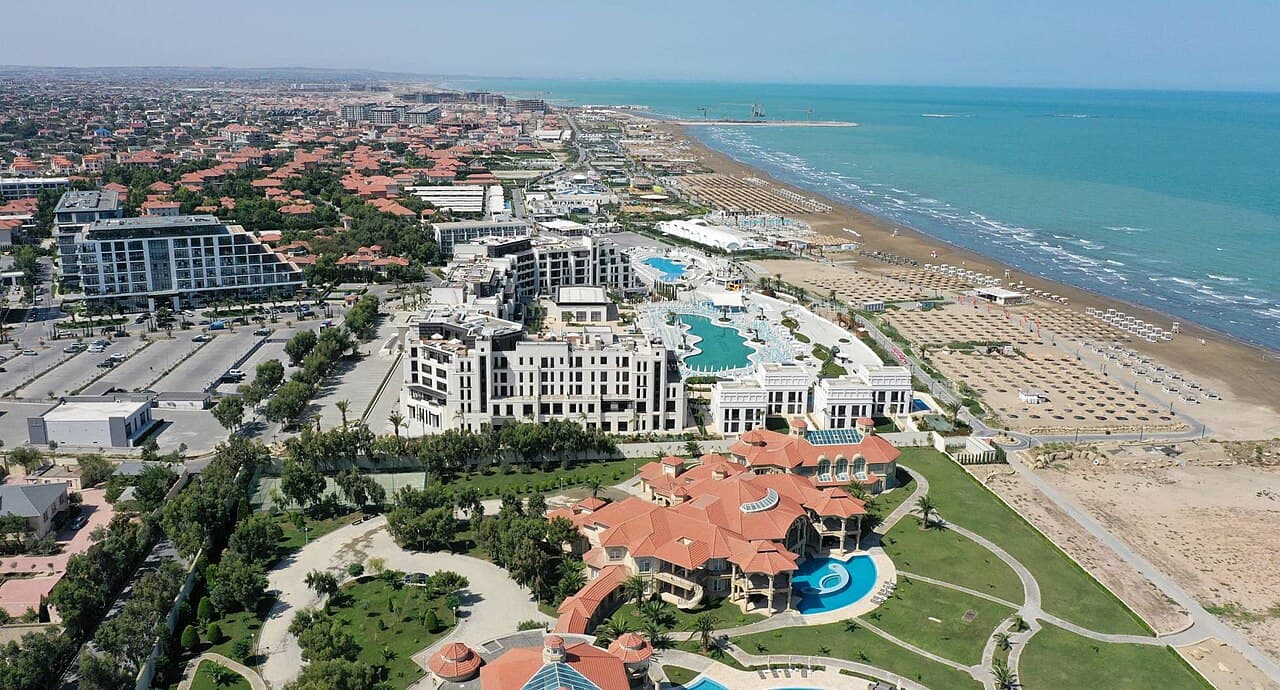
On 24 August 2026, Hagag Group - a publicly listed Israeli real estate developer - reported to the Tel Aviv Stock Exchange that it had signed memoranda of understanding for two residential plots inside Sea Breeze, on the Caspian coast north of Baku. It is the largest single foreign entry into this coastline announced to date, and it is also the most widely misunderstood, because almost every element of it is conditional.
This page sets out exactly what was reported, in the words of the reporting, and marks the boundary between the agreed and the assumed.
What Was Signed
| Item | As reported |
|---|---|
| Instrument | Memoranda of understanding - not binding agreements |
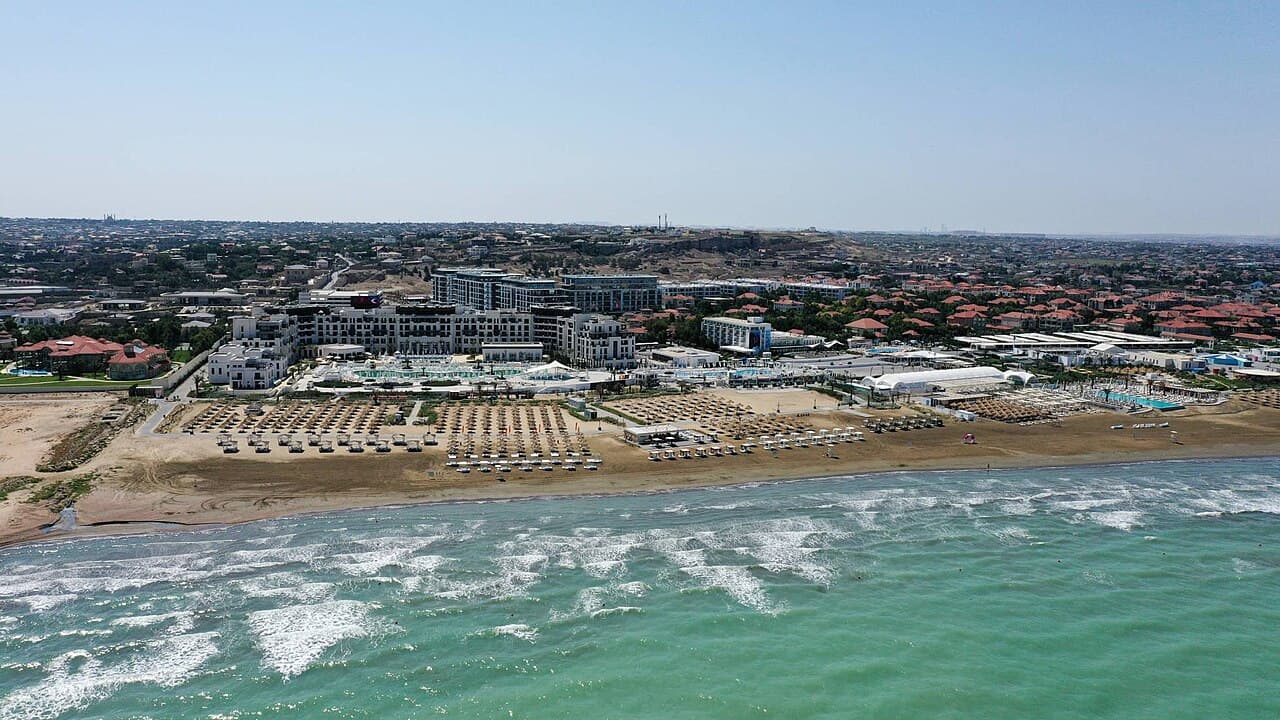
| Asset | Land for two residential projects inside Sea Breeze, described as first line to the sea |
| Scale | Project one ~2,475 units; project two ~1,000 units; ~3,500 units total |
| Built area | ~358,000 sqm combined |
| Land cost | Up to $93 million across both transactions |
| Payment | Most of the land cost expected to be paid out of proceeds from apartment sales rather than upfront |
| Ownership | Hagag ~80%; a local partner ~20% |
| Local partner | Not named in any report |
| Reported entry price | From around $150,000 per apartment |
| Condition | Due diligence "in the coming month", then final terms |
The reporting also carried a statement from Tzachi and Ido Hagag, the group's co-chief executives and controlling shareholders: "We identified a real estate market in enormous development momentum."
The Three Words That Matter
Memoranda of understanding. Not a purchase, not a binding contract, and not a commitment by either side to complete. An MOU records that the parties have agreed a framework. The Israeli reporting was explicit on this, describing the transaction as being at a stage preceding binding agreements.
Land. This is a land acquisition for future development, not the purchase of an existing project. There are no apartments to look at, no building, and no delivery date - because there is nothing yet to deliver. Any claim that Hagag has bought a Sea Breeze project, or is selling apartments there, is wrong.
Up to. The $93 million figure is a ceiling across two transactions, not a price paid.
The Payment Structure Is the Interesting Part
The reported structure is that most of the land cost would be met out of the proceeds of apartment sales rather than from equity paid at the start. That is a common arrangement in large land deals and it has a specific consequence: the deal's viability is tied to sales velocity.
If apartments sell quickly, the land largely pays for itself and the return on the equity actually committed is high. If sales are slow, the developer must fund the shortfall from elsewhere, which affects both the construction timetable and the return. For a buyer, that creates an unusual alignment to be aware of - early sales are not just revenue, they are the mechanism that funds the land - and it is one reason to ask hard questions about launch pricing.
Taken at the reported entry price of around $150,000, 3,500 apartments represents more than $500 million of eventual sales value, before any variation in size, specification or pricing over time. That is the scale of what is being contemplated, and it is roughly the sales value of a mid-sized Israeli project, executed in a market with no comparable track record for this company.
What Is Not Known
Which plots. No plot identification, no position within the masterplan beyond "first line to the sea", and no indication of which neighbouring projects they adjoin.
Who the counterparty is. Reports do not identify the seller of the land. Agalarov Development is the master developer at Sea Breeze, but no report we found names it as the vendor in this transaction.
Who the local partner is. The 20% holder is unnamed in every report. Several companies active at Sea Breeze would be plausible, and naming one on that basis would be a guess rather than a finding.
Any construction timetable. No design, no permitting status, no start date, no delivery date.
Whether the deal has advanced. Due diligence was described as happening within a month of 24 August 2026 - that is, during September. As of late October, no public announcement of binding agreements has appeared, and none of a withdrawal either. See our status tracker for the current position, which is updated as filings appear.
What 3,500 Units Would Do to Supply
Scale is the part of this story that gets lost behind the word "memorandum". Sea Breeze's existing delivered stock across twenty years of phases plausibly runs to several thousand apartments. A single new entrant proposing roughly 3,500 units in two projects is therefore not an incremental addition - it is a material expansion of the resort's housing supply, delivered by one company over a few years.
For an existing owner that cuts both ways. More supply on the same coastline means more competition when you let and when you sell, particularly if the new stock is newer, better specified and launched with developer payment plans you cannot match as a private seller. It also means more residents, which supports the shops, the school and the services that make a resort function year-round - the thing that currently constrains winter demand.
Which effect dominates depends on absorption. If 3,500 units arrive into rising foreign demand, the resort densifies and everyone benefits. If they arrive into a soft market, they compete directly with the stock sold at today's prices. Either way, the right question for anyone buying nearby is simple: what is planned adjacent to my building, by whom, and when - and this deal is now part of that answer.
Why an Israeli Listed Company Changes the Information Picture
There is one practical advantage to a deal involving a company listed in Tel Aviv, and it has nothing to do with nationality: disclosure.
A listed company must report material developments to the stock exchange. That means the next real information about this transaction will arrive as a filing, in public, on a date nobody controls - not as a sales office's reassurance. If the deal becomes binding, there will be a filing. If it is abandoned, there will usually be a filing. If the terms change materially, the same.
That is a far better information environment than most of this coastline offers, where the alternative is a developer's own website behind a Cloudflare challenge and a brochure with no date on it. For once, the honest instruction to a buyer is not "ask the agent" but "read the filings", and anyone can.
How to Judge It
Two reference points help more than any brochure.
The company's own overseas record. Hagag Development Europe has invested more than EUR 150 million in Bucharest, completed H Victoriei 139, and has H East Residence in progress - a scheme whose first phase moved from an expected end-2025 completion to the fourth quarter of 2026. That is ordinary in development, and it is the best available evidence of how this group's foreign timetables behave.
The resort's own stage of completion. In September 2026 Emin Agalarov said only 10-15% of Sea Breeze's planned work had been completed, with seven to eight years to implement everything designed. A 3,500-unit addition would be a significant share of the resort's future supply, and its own timetable sits inside that longer one.
Our developer scorecard places Hagag against the other companies building at Sea Breeze, and the full project inventory shows what the surrounding pipeline already contains.
The Honest Summary
A listed Israeli developer has agreed a framework to buy two seafront plots at Sea Breeze for up to $93 million, intending roughly 3,500 apartments across about 358,000 square metres, holding 80% alongside an unnamed local partner, with most of the land payment expected to come out of future apartment sales.
None of that is a project yet. It is a serious, specific, publicly disclosed intention by a company with a real balance sheet - which is considerably more than most announcements about this coastline amount to, and considerably less than a development you could buy into today.
 New developments
White Villas: Sold Out, and Still Bookable by the Night
White Villas I is marked Sold on the resort's own page and phase II publishes no price at all - 170 delivered turnkey villas of 60-78.6 m², bookable but not buyable
Read more → New developments
Whitestone Beach at Sea Breeze: the Project Where You Can Reconstruct the Developer's Own Arithmetic
406 apartments, 41-125 m2, December 2027, from $102,000. 41 m2 times the advertised $2,500 is $102,500 - and the published entry price is $102,000. One of only two
Read more →New developmentsWho Designed Sea Breeze? The Five Architects Behind It
Scott Brownrigg, Killa Design, Melike Altinisik Architects, Adel Zehni and ELIE SAAB Maison - the named design authors of Sea Breeze, and what each one did
Read more →